The Cost of America First • Part III of The Price of Power
America First can extract concessions because allies depend on U.S. markets, weapons, technology and finance. But each use of that leverage gives Europe another reason to reduce dependency. The short-term gains may be real. So is the long-term cost to American power and its wider global influence.
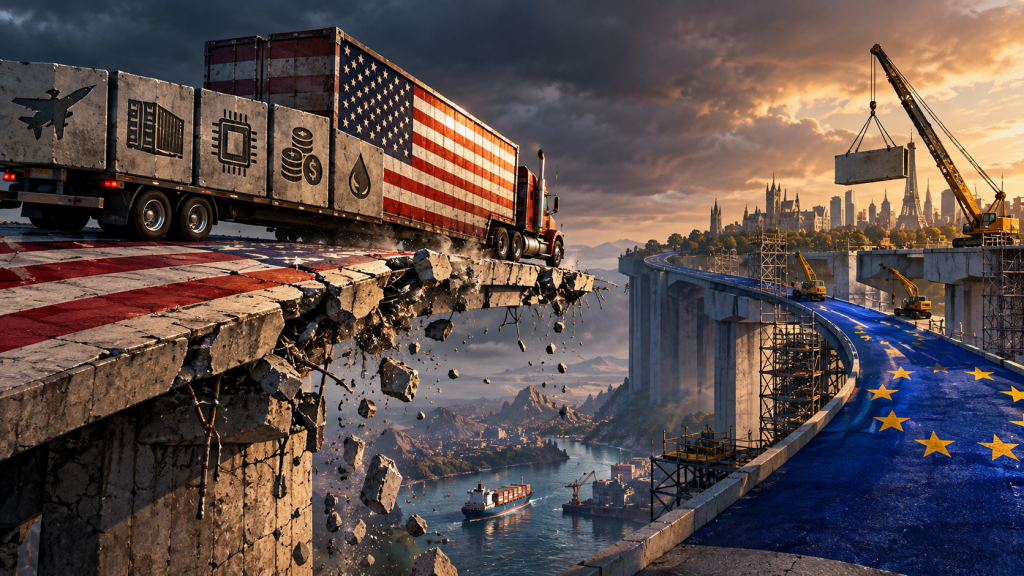
For most of the postwar era, the United States benefited from being the country its allies could afford to depend on. Europe bought American weapons, held American financial assets, relied on American technology and built much of its security around an American military guarantee. As the first two articles in this series showed, those relationships cost Washington real money, but they also produced markets, investment, influence and strategic reach.
That arrangement depends on more than American power. It also depends on confidence that the United States will remain a predictable partner.
The Trump administration has put that assumption under pressure. Its trade policy uses tariffs as leverage. Its defence policy has pushed allies to carry more of their own burden. President Donald Trump has repeatedly linked American security commitments to allied spending, while his administration has treated market access and economic dependence as bargaining tools. Those policies can extract concessions in the short term. They can also give America’s allies a reason to reduce the dependencies that make such pressure effective.
Europe is not abandoning the United States. American markets remain vital, U.S. military capabilities remain important to NATO, and American technology remains deeply embedded in European economies. Yet European governments are now discussing dependence on the United States in language once reserved mainly for Russia and China.
That change is the real cost worth examining.
Dependence Becomes a Political Risk
Trump has long argued that NATO members should spend more on defence. That complaint did not begin with him, and European underinvestment was real. As Part II examined, many European governments allowed military capacity to decline after the Cold War while relying heavily on American intelligence, logistics, air defence and other capabilities.
Trump changed the tone of that debate by questioning whether the United States should defend allies that he believed were spending too little. In March 2025, he told reporters that if NATO members did not “pay,” he would not defend them. Three months later, after allies agreed at The Hague to move toward spending 5 per cent of GDP on defence and related security by 2035, Trump reaffirmed support for NATO’s Article 5 collective-defence commitment.
The immediate outcome was a major increase in European defence commitments. The White House now presents that shift as one of the administration’s central foreign-policy successes. It also points to tens of billions of dollars in allied purchases of American military equipment as an economic benefit for the United States.
Yet the same pressure has encouraged Europe to ask a second question. If American protection can become conditional on Washington’s changing political demands, how much of Europe’s security should remain dependent on American systems?
That does not mean Europe expects the United States to leave NATO tomorrow. It means planners must consider a risk that many governments previously treated as remote. Military procurement decisions last for decades. A fighter aircraft, missile system or intelligence network bought today may still be operating under several future American administrations.
Once uncertainty enters that calculation, strategic autonomy stops being an abstract political slogan. It becomes insurance.
Tariffs Changed the Economic Calculation
The same logic applies to trade.
The Trump administration has made tariffs a central instrument of economic policy. Its 2025 trade confrontation with the European Union ended in a framework that placed a 15 per cent tariff ceiling on most EU goods entering the United States. The EU also agreed to eliminate tariffs on U.S. industrial goods and improve market access for selected American agricultural products. Both Washington and Brussels described the agreement as a way to stabilize one of the world’s largest trade relationships after months of uncertainty.
From Washington’s perspective, this demonstrated the usefulness of American market power. The White House openly celebrated the agreement as evidence that tariffs could secure greater market access, investment and energy purchases from Europe.
For Europe, however, the experience also demonstrated the risk of relying too heavily on access to the American market.
The United States is one of Europe’s most important trading partners. That makes access to American consumers valuable, but it also gives Washington leverage. The more concentrated that dependence becomes, the more disruptive any future tariff threat can be.
Europe therefore has an incentive to diversify even if relations with the United States remain broadly cooperative. Trade agreements with other regions do not need to replace the American market. They only need to reduce the damage if access to that market becomes less predictable.
This is one of the recurring contradictions of economic pressure. Leverage works because the other side depends on something you control. Repeated use of that leverage encourages the other side to seek alternatives.
Greenland Made the Risk Harder to Ignore
That contradiction became far more visible during the Greenland dispute in January 2026.
Trump intensified his campaign for U.S. control of Greenland, an autonomous territory within the Kingdom of Denmark. He threatened additional tariffs against European countries that opposed the effort. Denmark is not an adversary of the United States. It is a NATO ally.
European Council President António Costa responded by saying that tariffs would undermine transatlantic relations and would be incompatible with the U.S.-EU trade agreement reached only months earlier. He also said the EU was ready to defend its members against “any form of coercion.”
The language matters because it came from an institution committed to preserving the transatlantic alliance. European leaders did not declare the United States an enemy or call for economic separation. They continued to stress cooperation with Washington and NATO.
They also convened an extraordinary European Council meeting to discuss the implications for the relationship with the United States. After Trump withdrew the additional tariff threat, Costa welcomed the change but said Europe would continue building a “more strategically autonomous” union.
The sequence was difficult to miss. Europe had reached a trade agreement with Washington in the summer of 2025 in part to restore predictability. Within months, tariffs were again being threatened, this time over the territory of a NATO ally.
Even though the immediate confrontation eased, the underlying lesson remained. An agreement with Washington could not eliminate the political risk created by future American decisions.
Europe Started Mapping Its Dependencies
Three weeks after the Greenland confrontation, EU leaders met again. This time, the agenda went beyond the immediate dispute.
At their February 12 retreat, European leaders discussed how to reduce economic dependencies and strengthen the single market. Costa said there was broad agreement that Europe needed to identify and reduce vulnerabilities in strategic industries. Defence, space, clean technology, quantum computing, artificial intelligence and payment systems were all named. Leaders also discussed using a targeted “European preference” in some strategic sectors and expanding trade diversification.
These policies did not suddenly appear because of Trump. Europe had worried for years about dependence on Russian energy, Chinese manufacturing and American technology. France had promoted “strategic autonomy” long before Trump’s return to office.
The timing nevertheless matters. The debate has broadened from reducing dependence on adversaries to reducing dependence itself, including dependence on the United States.
That is a significant change.
Europe is no longer asking only whether an American product or service is efficient. It is increasingly asking whether control by a non-European supplier creates a strategic vulnerability.
The European Commission formalized that approach in June with a technological sovereignty package covering semiconductors, artificial intelligence, cloud computing and open-source software. The Commission said Europe remained heavily dependent on non-EU suppliers for core digital technologies and proposed measures intended to give European governments greater control over sensitive infrastructure.
The United States is not the only target of these policies. China is a major concern, especially in manufacturing and technology supply chains. Yet American companies dominate several areas in which Europe now wants more autonomy, particularly cloud services and digital infrastructure.
That means a policy designed around resilience can still reduce America’s economic position.
Financial Markets Have Started Asking the Same Question
The reassessment is not limited to governments.
In January, several major Northern European institutional investors told Reuters that geopolitical uncertainty was affecting how they viewed American assets. Swedish pension fund Alecta had sold most of its U.S. Treasury holdings, while Denmark’s AkademikerPension announced that it would sell about $100 million in Treasuries. Russell Investments said roughly half of the Northern European clients with which it was discussing the issue were considering whether to reduce their U.S. exposure.
Those decisions should not be misrepresented as a coordinated European campaign against the United States. AkademikerPension specifically said its Treasury decision reflected concern about American public finances rather than political retaliation over Greenland. Other investors continued to describe the United States as an attractive market.
However, they also said American policy uncertainty had become part of their risk assessment.
That distinction is important. Investors do not need to make political statements to create an economic consequence. If they decide that U.S. assets require a higher risk premium, even while continuing to invest heavily in them, the advantage America receives from being the world’s default financial destination weakens at the margin.
No mass European withdrawal from American markets is underway. The size and liquidity of U.S. markets make rapid financial separation unlikely, and American equities remain central to global portfolios.
What has changed is the discussion. European investors are openly asking whether concentrated exposure to the United States remains as safe as they once assumed.
Payments and Currency Are Becoming Strategic
The European Central Bank is asking a similar question about financial infrastructure.
In February, ECB Executive Board member Piero Cipollone argued that Europe had become excessively dependent on foreign providers in payments and finance. He warned that, in a world where dependencies can be used as leverage, Europe could no longer outsource functions that were critical to its economic security.
The practical response is already taking shape. In September, European payment providers announced the European Network for Payments, which will connect systems serving roughly 130 million users across 13 countries. One of its stated objectives is to reduce reliance on American payment networks such as Visa and Mastercard.
The ECB is also working to strengthen the euro’s international role. On September 28, ECB President Christine Lagarde said the bank would expand work on swap arrangements that make euros available to foreign central banks during periods of stress. Reuters reported that the move comes amid wider concern about financial fragmentation and uncertainty over the future international role of the dollar.
None of these developments threatens dollar dominance in the immediate future. The euro still lacks the depth of American capital markets, and the dollar remains the world’s leading reserve currency.
The significance lies elsewhere. Europe is building mechanisms that give it more choices.
Every alternative payment network, every European cloud provider, every additional defence-production line and every trade agreement outside the transatlantic market reduces one form of dependency. None of them needs to replace the United States to change the balance of leverage.
Defence Shows the Contradiction Most Clearly
The contradiction is especially sharp in defence.
The Trump administration wants Europe to spend more, and Europe is doing so. The White House also wants a substantial share of that spending to support American industry. It noted this year that NATO allies bought more than $54 billion in U.S. defence equipment during 2025 alone.
At the same time, Europe has begun expanding its own defence-industrial policies. SIPRI found that U.S. weapons still supplied 58 per cent of major arms imported by European NATO countries during 2021–25. It also noted that uncertainty about America’s commitment to European defence has added to demand for weapons and encouraged debate over greater European self-reliance.
Washington therefore faces two possible outcomes from the same policy.
If Europe spends more while continuing to buy mainly American systems, the United States gains stronger allies and more defence exports. If Europe spends more while shifting procurement toward European companies, Washington gains stronger allies but loses part of the industrial and political leverage that came with European dependence.
The second possibility is becoming more plausible because European governments increasingly view defence production as a sovereignty issue rather than simply a purchasing decision.
That shift will be the subject of Part IV of this series.
America Is Not Being Replaced
It would be easy to overstate the change.
Europe is not decoupling from the United States. NATO remains the foundation of European collective defence. American military capabilities still fill important gaps. U.S. companies remain dominant in cloud computing, software and many advanced technologies. European investors still hold enormous quantities of American securities, while the transatlantic trade relationship remains one of the largest in the world.
Europe also has its own divisions. Member states do not agree on how far strategic autonomy should go, how much preference European companies should receive or how quickly dependence on foreign suppliers can realistically be reduced.
Nor can every European sovereignty initiative be attributed to Trump. Russia’s invasion of Ukraine provided the strongest reason for Europe’s military buildup. Dependence on China drove much of the concern about supply chains and manufacturing. The euro and digital sovereignty projects have roots that predate the current administration.
The Trump administration’s role is better understood as an accelerator.
It has shown European policymakers that economic and security dependence on the United States can become part of a negotiation. Once that possibility becomes credible, governments have a rational reason to insure against it, even if they still expect the alliance to survive.
That is why strategic autonomy is moving from speeches into procurement rules, payment systems, technology policy and investment decisions.
The Price of Leverage
America First is designed to use American power more directly for American advantage. The United States has the world’s largest consumer market, deep capital markets, leading technology companies, a dominant currency and military capabilities that its allies still need. Those assets give Washington considerable negotiating power.
The administration has demonstrated that this pressure can produce results. European defence spending has risen. The United States secured a new trade framework with the EU. American defence manufacturers continue to benefit from European rearmament.
The longer-term question is what happens when those same successes change European behaviour.
The leverage available to Washington exists because allies depend on systems the United States controls or dominates. Tariffs matter because the American market matters. Security pressure matters because American military capabilities matter. Technology restrictions matter because American platforms matter. Financial policy matters because the dollar and American capital markets matter.
If Europe concludes that those dependencies carry a larger political risk, it has an incentive to reduce them.
The change will not happen through one dramatic break. It will happen through a series of smaller decisions: another weapons contract awarded inside Europe, another trade agreement signed elsewhere, another cloud service brought under European control, another payment network built without American intermediaries and another reserve option strengthened alongside the dollar.
Each decision may appear modest on its own. Together, they can alter a system that took decades to build.
The first article in The Price of Power showed how much the United States gained from an international order centred on American markets, institutions and influence. The second showed that NATO itself has generated strategic and commercial benefits alongside its costs.
The third reveals the vulnerability inside that system. American leverage is strongest when allies believe dependence on the United States is safer than the alternatives.
America First can use that dependence to extract concessions. It can also make reducing that dependence look increasingly prudent.
Those two outcomes are now unfolding at the same time.
Sources
European Council — Greenland statements and January 2026 meeting on transatlantic relations. European Council statement on Greenland
European Council — February 2026 leaders’ retreat on strategic industries, diversification and reducing dependencies. European Council leaders’ retreat
European Commission — EU technological sovereignty package covering cloud, AI, semiconductors and open-source technology. European Technological Sovereignty Package
European Central Bank — Piero Cipollone on monetary sovereignty and the strategic risks of financial dependencies. Europe and monetary sovereignty
SIPRI — European arms imports, U.S. market share and growing debate over European defence self-reliance. Global arms flows and European demand
Reuters — Northern European institutional investors reassessing exposure to U.S. assets amid geopolitical and fiscal uncertainty.